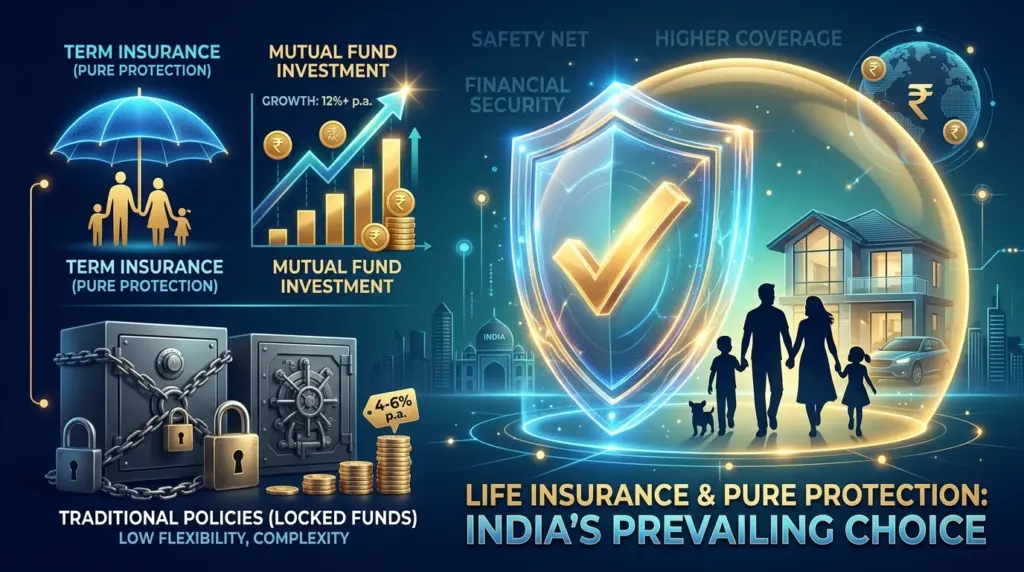
Understanding Life Insurance: Types, Benefits, and Why Term Insurance Prevails in India
⚡ The Core Financial Verdict
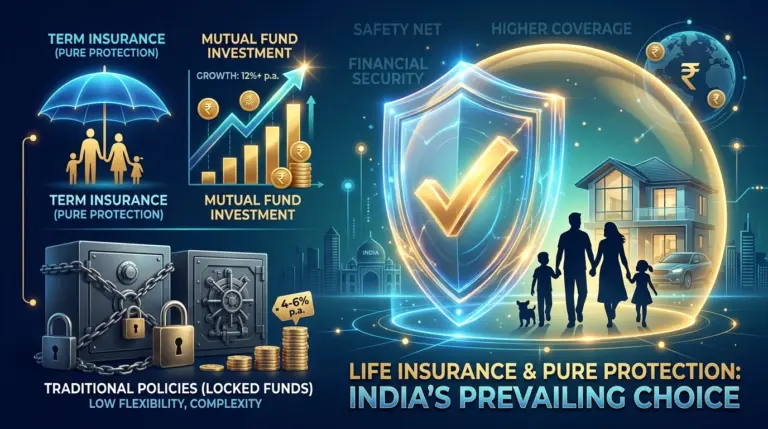
Insurance is an expense to protect dependents against catastrophe—not an investment instrument. In every mathematical model, combining a high-cover Pure Term Insurance Plan with disciplined Equity Mutual Fund SIPs generates 3x to 6x higher wealth at retirement compared to bundled Endowment, Money-Back, or traditional Whole-Life policies, while delivering 10x higher financial security to your family from Day 1.
If you have elderly parents, a spouse, or young children dependent on your monthly paycheque, the untimely demise of the primary breadwinner is not just an emotional tragedy—it is an instantaneous financial catastrophe. Outstanding home loans, credit card balances, children's school and university fees, and day-to-day household expenses do not pause for grieving families.
In the Indian financial landscape, life insurance is often marketed as a pious ritual: uncle agents visit during festive seasons, bank relationship managers push "guaranteed child plans" before March 31 tax deadlines, and glossy advertisements promise "returns with life cover." Yet, over 70% of Indian households remain dangerously underinsured, holding traditional policies with average covers of barely ₹3 Lakhs to ₹5 Lakhs—an amount that would hardly sustain a family for eighteen months in any tier-1 or tier-2 Indian city.
This master guide cuts through the commercial noise. We will demystify every category of life insurance available in India, analyze their structural mechanics under IRDAI regulatory frameworks, mathematically demonstrate why pure term insurance prevails over every other alternative, and examine vital safeguards like Section 45 of the Insurance Act and the Married Women's Property Act (MWP Act).
Table of Contents: Complete Master Guide
- 1. The 6 Types of Life Insurance in India →
- 2. Life Insurance Comparison Matrix →
- 3. Why Term Insurance Prevails: The Math →
- 4. The "Return of Premium" (TROP) Trap →
- 5. How Much Cover Do You Need? (HLV Rule) →
- 6. Essential Riders vs Standalone Policies →
- 7. Section 45 & The MWP Act Protection →
- 8. Decoding CSR & Amount Settlement Ratios →
- 9. Income Tax Rules & Section 10(10D) Caps →
- 10. Why Agents Push Endowment Over Term →
- 11. 7 Fatal Mistakes When Buying Term Cover →
- 12. Frequently Asked Questions (FAQ) →
1. Understanding the 6 Major Types of Life Insurance in India
To make an informed decision, you must first understand the structural difference between pure protection contracts and bundled investment-cum-insurance contracts recognized by the Insurance Regulatory and Development Authority of India (IRDAI).
1. Pure Term Insurance
Term insurance is the purest and most straightforward form of life insurance. You pay a nominal annual premium for a pre-determined term (e.g., 30 to 35 years). If you pass away during the policy term, your nominee receives 100% of the Sum Assured (e.g., ₹1 Crore to ₹3 Crores). If you survive the term, the policy lapses with zero survival payout.
- Typical Cost: ₹10,000 – ₹16,000/year for ₹1 Crore cover (at age 30, non-smoker).
- Primary Objective: Maximum income replacement at minimum cost.
- Ideal For: Every salaried, self-employed, and business person with dependents.
2. Endowment Assurance Plans
Endowment plans bundle life cover with a traditional debt savings corpus. A portion of your premium covers mortality risk, while the insurer invests the remainder in government securities and bonds. In exchange, the insurer promises a guaranteed sum assured plus declared annual "bonuses" payable either on death or maturity.
- Typical Cost: ₹85,000 – ₹1,10,000/year for merely ₹10 Lakhs to ₹15 Lakhs cover.
- Historical Net Return: 4.5% to 5.5% p.a. (trailing inflation).
- Drawback: Painfully low coverage and hefty surrender penalties in early years.
3. Money-Back Policies
A variant of endowment assurance designed for psychological satisfaction. Instead of waiting for full maturity, policyholders receive periodic survival benefit payouts (e.g., 15% or 20% of the sum assured every 4 or 5 years), with the remaining balance paid upon maturity along with accrued bonuses.
- Typical Cost: Even higher premium than standard endowment plans.
- Historical Net Return: 4.0% to 5.0% p.a.
- Drawback: Periodic cash flows prevent compounding, eroding real purchasing power.
4. Unit Linked Insurance Plans (ULIPs)
ULIPs invest premium proceeds directly into debt and equity capital markets via fund units. While modern online ULIPs have lower charges than older offline versions, they still deduct Policy Administration Charges, Fund Management Charges, and Mortality Charges every month by cancelling units.
- Lock-in Period: Mandatory 5 years; poor liquidity during market crashes.
- Tax Cap: Tax-free only if aggregate annual premium is ≤ ₹2.5 Lakhs (Finance Act 2021).
- Drawback: If equity markets plunge, both your corpus and mortality unit deductions suffer.
5. Whole Life Insurance
Unlike term insurance that expires at retirement (age 60 or 65), whole life plans cover you up to age 99 or 100. Upon survival to age 100 or on prior death, the sum assured and terminal bonuses are disbursed to legal heirs as an estate inheritance tool.
- Target Audience: High Net-Worth Individuals (HNIs) for inter-generational estate planning.
- Drawback: Premiums are significantly higher than pure term plans; unnecessary for middle-income earners whose financial liabilities terminate by age 60.
6. Child Education & Pension Plans
Child plans offer a "Waiver of Premium" clause ensuring that if the parent dies, the insurer pays future premiums and releases funds when the child turns 18. Pension plans accumulate a corpus that must be converted into an immediate annuity (which is fully taxable at slab rates upon receipt).
- Alternative: Pure term cover for parents + dedicated Mutual Fund SIPs in the parent's name achieves far superior flexibility and tax efficiency.
2. Life Insurance Comparison Matrix: Features, Costs & Returns
Here is how the common life insurance options compare across the metrics that matter most to Indian families:
| Insurance Category | Sum Assured for ₹25,000/yr Premium | Investment Component | Expected Net Returns (CAGR) | Liquidity & Surrender | Verdict |
|---|---|---|---|---|---|
| Pure Term Insurance | ₹1.50 Crore – ₹2.00 Crore | None (Pure Protection) | N/A (Safety Net) | Can cancel anytime; zero surrender penalty | Essential Must-Have |
| Endowment Plan | ₹3.00 Lakhs – ₹4.00 Lakhs | Conservative Debt/Bonds | 4.5% – 5.5% | Heavy surrender losses in Years 1–3 | Underinsures Family |
| Money-Back Policy | ₹2.20 Lakhs – ₹3.00 Lakhs | Conservative Debt/Bonds | 4.0% – 5.0% | Rigid payout schedule; poor exit terms | Inflation Destroyer |
| Online ULIP | ₹2.50 Lakhs (10x annual premium) | Equity & Debt Units | 8.0% – 10.5% (Market linked) | 5-Year Strict Lock-in; partial withdrawals later | Sub-optimal Bundle |
| Whole Life Plan | ₹5.00 Lakhs – ₹8.00 Lakhs | Cash value accumulation | 5.0% – 6.0% | Policy loans permitted after 3 years | Expensive Cover |
3. Why Term Insurance Prevails: The Unvarnished Mathematical Proof
The single most powerful financial strategy for any earning individual is known globally as "Buy Term and Invest the Difference" (BTID). To understand why this strategy dominates, let us look at a real-world financial simulation for a 30-year-old Indian professional.
📊 The 30-Year Head-to-Head Simulation: Age 30 to Age 60
Profile: Healthy 30-year-old non-smoker with a target life cover of ₹1 Crore and an investable budget of ₹50,000 per year.
💡 The Stark Contrast: By separating insurance from investments, Strategy B gives your family 11.7 times higher life protection from Day 1 and yields ₹76.9 Lakhs more wealth at retirement! You can test varying contribution amounts using our interactive SIP Wealth Calculator.
Why does Strategy B crush traditional policies? The answer lies in compounding without excessive friction:
- In an endowment policy, 20% to 35% of your first-year premium is siphoned off as distributor commissions, administrative charges, and mortality loadings. The remaining corpus is restricted by regulation to low-yielding sovereign debt instruments yielding 6% to 7% gross, which after expenses leaves you with a paltry 4.5% to 5.5% net return.
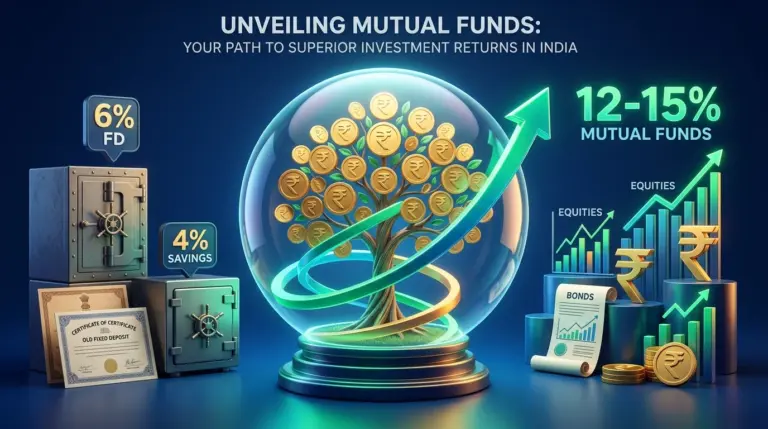
- In contrast, a pure term plan uses only ₹12,000 for pure mortality pooling. The remaining ₹38,000 enters high-growth Indian equity assets via mutual funds, where long-term compounding at 12% to 14% CAGR creates monumental wealth over two to three decades.
4. The "Term with Return of Premium" (TROP) Trap Exposed
A classic marketing hook used by insurers is the TROP (Term with Return of Premium) policy. The agent tells you: "Why throw away your money on regular term insurance where you get nothing if you survive? Take our TROP plan—if you survive, we will refund every single rupee you paid!"
To an untrained eye, getting "free insurance" sounds irresistible. In reality, TROP is one of the most profitable products for insurance companies and a massive financial loss for policyholders.
⚠️ The Hidden Opportunity Cost of TROP Plans
- Regular Term Plan: ₹1 Crore cover for 30 years costs approximately ₹12,000/year. Total 30-year payment = ₹3,60,000.
- TROP Plan: Exactly the same ₹1 Crore cover costs approximately ₹32,000/year (nearly 2.7x higher!). Total 30-year payment = ₹9,60,000.
- At age 60, the TROP insurer proudly returns your ₹9,60,000 back to you with zero interest.
- What Did You Actually Lose? The extra ₹20,000 per year (₹1,666/month) you gave the insurer, if invested in a simple index fund or flexi-cap mutual fund at 12% CAGR, would have grown to over ₹58.8 Lakhs!
By taking a TROP plan to get back ₹9.6 Lakhs, you surrendered nearly ₹59 Lakhs of wealth creation. Never buy Return of Premium plans. Stick to regular pure term insurance.
5. How Much Life Cover Do You Actually Need? The Human Life Value (HLV) Method
The biggest mistake in life insurance is arbitrary guessing. Taking a ₹25 Lakh or ₹50 Lakh policy might sound like a massive sum today, but with 6% annual inflation, ₹50 Lakhs in 15 years will have the purchasing power of barely ₹20 Lakhs today.
📐 The Scientific 3-Pillar Formula for Term Cover
To ensure your family is completely shielded against debt collectors and lifestyle degradation, use the Expense & Liability Replacement Formula:
Practical Example:
- Annual Household Expenses: ₹8 Lakhs/year → 20x replacement fund = ₹1.60 Crores.
- Outstanding Home Loan: ₹45 Lakhs.
- Children's College Fund Target: ₹35 Lakhs.
- Existing Liquid Investments: ₹20 Lakhs (in EPF, PPF, and mutual funds).
- Ideal Term Cover Required: ₹1.60 Cr + ₹45 L + ₹35 L − ₹20 L = ₹2.20 Crores. Round up to ₹2.50 Crores for a comfortable safety buffer.
6. Essential Riders to Strengthen Your Term Policy (And Which Ones to Skip)
Insurers offer optional policy add-ons called riders. While some provide indispensable catastrophic protection, others are expensive gimmicks best purchased as standalone policies.
| Rider Name | What It Covers | Recommendation | Why? |
|---|---|---|---|
| Waiver of Premium (WOP) on Critical Illness / Disability | If you are diagnosed with a listed critical illness or suffer permanent total disability, all future term premiums are waived while your full life cover stays active. | Highly Recommended | Inexpensive rider that keeps your life cover alive when your earning capability is severely impaired. |
| Critical Illness Rider | Lump-sum payout upon diagnosis of 30+ major illnesses (heart attack, cancer, stroke, kidney failure). | Consider (Check Terms) | Opt for an additional benefit rider rather than an accelerated rider (which reduces your base death cover upon claim). Alternatively, buy a standalone comprehensive critical illness policy. |
| Accidental Death & Disability Rider | Additional payout (e.g., extra ₹50 Lakhs) if death occurs due to an accident, or periodic income if permanent disability occurs. | Recommended | Very inexpensive add-on providing financial relief for sudden traumatic accidents on Indian roads. |
| Terminal Illness Benefit | Accelerated payout if doctors certify life expectancy of less than 6 months. | Built-in (Usually Free) | Most top-tier insurers now include this built-in at zero extra cost. |
7. Critical Legal & Regulatory Safeguards: Section 45 and the MWP Act
Many policyholders live in constant anxiety: "What if the insurer rejects my family's claim after I am gone?" To protect honest policyholders, Indian law provides two ironclad shields:
A. Section 45 of the Insurance Act, 1938 (3-Year Incontestability Clause)
Amended under the Insurance Laws (Amendment) Act, Section 45 states that no life insurance policy can be called into question, repudiated, or rejected by an insurer on any ground whatsoever after the expiry of three continuous years from policy issuance or revival.
- During the first three years, insurers have the legal right to investigate and reject claims if fraud or intentional non-disclosure of pre-existing health conditions or smoking habits is uncovered.
- After 3 continuous policy years, the insurer cannot reject a claim, even alleging non-disclosure or misstatement. This provides absolute peace of mind for your family.
B. Section 6 of the Married Women's Property Act, 1874 (MWP Act)
If you are a business owner, partner in a firm, self-employed professional, or an individual with substantial bank loans, buying your term policy under the MWP Act is non-negotiable.
- When a policy is endorsed under Section 6 of the MWP Act at the time of proposal, it forms an irrevocable trust solely for the benefit of your wife and/or children.
- The Legal Shield: The policy proceeds can NEVER be attached by creditors, recovery agents, court orders, tax authorities, or business partners to clear your debts. The money goes directly and exclusively to your wife and children.
- Important Condition: MWP Act endorsement can ONLY be selected at the time of purchasing the policy. It cannot be added retrospectively later.
8. Decoding Claim Settlement Ratios: Why CSR Alone Is Misleading
Every insurance company markets its Claim Settlement Ratio (CSR), proudly displaying numbers like 98.5% or 99.2%. However, relying solely on overall CSR published in IRDAI annual reports can be deceptive.
🔍 The Three Ratios You Must Cross-Check:
- Claim Settlement Ratio by Number: The percentage of total claim applications approved. Top insurers (HDFC Life, ICICI Prudential, Tata AIA, Max Life, SBI Life) consistently maintain CSRs above 98.5%.
- Benefit / Amount Settlement Ratio: The percentage of the total claim value (in Rupees) disbursed. If an insurer settles 99% of small ₹2 Lakh claims but scrutinizes and delays ₹2 Crore term claims, their Amount Settlement Ratio will plunge to 91% or 92%. Always insist on insurers with an Amount Settlement Ratio above 95%–96%.
- Claim Repudiation Ratio: The percentage of claims rejected outright. Ensure repudiations are strictly under 1.0% to 1.5%.
9. Income Tax Implications for Life Insurance Policies
Taxation around life insurance has undergone dramatic reforms over recent Union Budgets. Understanding these distinctions ensures you do not trigger unexpected tax penalties upon maturity.
| Section | Tax Benefit / Provision | Key Limits & Amendments |
|---|---|---|
| Section 80C (Old Regime) | Deduction on premium paid up to ₹1.50 Lakhs per financial year. | Available only if premium is ≤ 10% of the sum assured. Note: Under the New Tax Regime (default tax system), Section 80C deductions are not available. |
| Section 10(10D) — Death Benefit | Death benefit payout received by nominees upon death of the life insured. | 100% Tax-Free across all categories of life insurance without any upper rupee ceiling! |
| Section 10(10D) — Traditional Maturity Cap | Maturity proceeds of traditional endowment, money-back, and whole-life policies. | Finance Act 2023 Rule: For policies issued on or after April 1, 2023, if aggregate annual premium exceeds ₹5,00,000, maturity gains are fully taxable at slab rates! |
| Section 10(10D) — ULIP Maturity Cap | Maturity proceeds of Unit Linked Insurance Plans. | Finance Act 2021 Rule: For ULIPs issued on or after Feb 1, 2021, if aggregate annual premium exceeds ₹2,50,000, maturity gains are treated as capital gains! |
10. The Profit-Driven Insurance Machine: Why Agents & Banks Push Endowment
If term insurance is indisputably superior for families, why do 80% of policies sold in India remain traditional endowment and money-back schemes? The answer comes down to financial incentives:
- Distributor Commissions: On a ₹12,000 term plan, the agent earns a nominal commission of ₹1,000 to ₹1,500 in Year 1, dropping to negligible amounts thereafter. On an endowment plan with an annual premium of ₹1,00,000, the first-year commission can range between 25% to 35% (₹25,000 to ₹35,000), plus generous renewal kickbacks and international vacation conventions.
- Bancassurance Targets: Relationship managers at commercial banks are assigned strict quarterly fee-income targets. Selling high-ticket endowment and guaranteed return schemes generates massive non-interest fee income for the bank at your expense.
- Exploiting Psychological Biases: The aversion to "losing premium if I don't die" is exploited by salespeople to sell low-yielding savings policies that leave your family underinsured.
11. 7 Fatal Mistakes to Avoid When Buying Term Insurance in India
- Hiding Smoking, Vaping, or Alcohol Consumption: Even occasional social smoking must be declared. If lung or heart complications arise within 3 years and nicotine traces are verified, the insurer will reject the claim for fraudulent non-disclosure. Pay the marginal non-smoker premium difference for 100% claim certainty.
- Depending Solely on Corporate Employer Cover: Employer group life insurance ends the day you resign, are laid off, or switch jobs. Buying individual term cover when you are in your 40s or 50s will cost 3x higher and carries the risk of medical rejection if lifestyle ailments (diabetes, hypertension) have developed.
- Choosing Coverage Till Age 85 or 99: Unless you have special-needs dependents, buying term insurance beyond age 60 or 65 is an unnecessary waste of money. By retirement, your home loan is paid off, your children are financially independent, and your accumulated wealth provides financial security.
- Letting the Agent Fill Your Proposal Form: Never sign a blank proposal form. Unscrupulous agents frequently tick "No" to previous family medical history or pre-existing hospitalizations to ensure fast policy issuance and commission clearance. Always verify every disclosure yourself.
- Skipping Physical / Tele-Medical Checkups: Policies issued without medical checkups (tele-issuance or salary-slip issuance) undergo stricter investigation at the time of claim. Insisting on a comprehensive medical checkup creates an official insurer-verified medical record, leaving no room for claim dispute later.
- Ignoring the Married Women's Property Act (MWP Act): If you run a business or have home loans, failing to select the MWP Act option leaves your insurance payout vulnerable to creditors.
- Not Informing Your Nominee: Ensure your spouse and family know where the physical policy document, policy number, and customer care contact details are kept. A term policy is worthless if the nominee does not know it exists.
Watch: Personal Finance & Wealth Masterclasses
Explore our deep-dive video masterclasses on insurance planning, mutual fund portfolio construction, and financial independence on the official InvestPlenty channel.
12. Frequently Asked Questions (FAQ)
Q1. Can Non-Resident Indians (NRIs) buy term insurance from Indian insurers?
Yes, absolutely. NRIs can purchase term insurance from Indian insurers either during a physical visit to India or from their country of residence via Video Medical Examination (tele-medical checkup). Premiums can be paid in foreign currency or via NRE/NRO accounts, and payouts are fully repatriable under FEMA guidelines. Read our detailed NRI Term Insurance Buying Guide for step-by-step instructions.
Q2. Is it safe to buy term insurance online directly without an agent?
Yes. In fact, purchasing term insurance online directly through the insurer's portal is 15% to 25% cheaper because distribution commissions are eliminated. Furthermore, you retain complete control over medical history disclosures, avoiding errors introduced by agents.
Q3. What should I do if I already hold an expensive endowment or money-back policy?
Calculate the opportunity cost. If you have only paid 1 or 2 premiums, stopping further payments and taking the surrender hit often frees up cash flow that compounds to far greater wealth in mutual funds. If the policy is close to maturity (e.g., 18 years into a 20-year policy), convert it to a "Paid-Up" policy to preserve accumulated bonuses without sinking fresh cash into it. Always secure an adequate pure term plan before touching your existing cover.
Q4. Can a homemaker or non-earning spouse buy term insurance in India?
Traditionally, Indian life insurers required proof of independent income (ITR or salary slips) to issue pure term cover. However, under updated IRDAI guidelines, several insurers now offer special term plans for homemakers based on the earning spouse's income (up to 50% of the husband's term cover), recognizing the immense economic value of homemaking.
Q5. What happens if I stop paying term insurance premiums after 10 years?
Because pure term insurance carries no cash value or investment units, if you stop paying premiums after the 30-day grace period, the policy simply lapses. You receive no refund, but you owe nothing to the insurer. Your family was protected for the 10 years you paid.
Q6. Should I choose a regular pay term plan or limited pay (e.g., pay for 10 years)?
For most salaried individuals, regular pay (paying annually until age 60) is mathematically superior. Due to 6% inflation, the ₹14,000 premium you pay in Year 25 has the real economic burden of barely ₹3,500. Limited pay plans front-load your payments when money has high opportunity cost, unnecessarily boosting the insurer's cash reserves.
Q7. Can I hold two term insurance policies from different companies?
Yes. Splitting your cover (e.g., ₹1 Crore with Insurer A and ₹1 Crore with Insurer B) is a common strategy to diversify claim-settlement operational risk. However, you MUST disclose the existing policy details in the second insurer's proposal form; hiding an existing policy violates disclosure rules.
Q8. Will my nominee receive the claim payout in a lump sum or monthly instalments?
Most modern term plans let you choose between a 100% lump-sum payout, monthly income payout (e.g., 0.5% of sum assured monthly for 10 years), or a combination (50% lump sum + 50% monthly income). If your nominee is not financially experienced, the hybrid model prevents sudden mismanagement of a massive corpus.
Secure Your Family's Future with Unbiased Guidance
Do you need help calculating your exact Human Life Value, evaluating existing endowment policies, or selecting the right term plan under the MWP Act? Consult with an AMFI-registered distributor committed to 100% transparent financial education.
Thank you for the informative post! It was an enjoyable read. I’d love to know more and stay in touch—any chance we could connect?
I am not sure where youre getting your info but good topic I needs to spend some time learning much more or understanding more Thanks for magnificent info I was looking for this information for my mission